Why Cities & States are Pushing Back Against the Cashless Trend
BFC Enterprises • April 8, 2025
With no federal law in place that requires private businesses to accept cash, a number of U.S. cities and states have taken steps in recent years to halt the movement towards a cashless society – and most importantly ensure low-income consumers, that don’t have access to traditional banking services, can fully participate in the economy.
Proponents of these laws argue cashless stores discriminate against the underbanked and poorer members of society that do not have access to bank accounts or credit/debit cards – and rely on cash to buy vital goods and services.
In addition to discrimination issues, cash is still a favored payment options for U.S. consumers despite the rise in credit/debit card and digital payment option. According to the Federal Reserve's
2024 Diary of Consumer Payment Choice, cash accounted for 16% of all consumer payments in 2023. Consumers under 55 using cash for 12% of their payments and those 55 and older using cash 22% of the time, according to a
2021 FDIC report.
Why the Cashless Trend is Bad for Business
Retailers and merchants who lean toward the cashless trend stand to alienate a large portion of their customers:
- Unbanked & Low-Income Consumers. Many U.S. citizens are still unaffiliated with a bank or credit union. Whether by choice, geographic location or socioeconomic factors, 18.6% Americans or approximately 24.6 million Americans are unbanked or underbanked and primarily deal solely in cash, according to a 2021 Federal Deposit Insurance Corporation report. While the number is at a record low, it is still a significant portion of consumers who would be unable to purchase goods or services in a cashless society.
- Young Shoppers. Since most credit cards have age limits and some type of income requirement, businesses that push for cashless payments stand to lose a fair number of customers – and profit – based on the age of their shoppers. Debit cards limit younger shoppers as well, since parents must cosign an account for driving age students, and anyone under the age of 15 is banned from opening a checking account – leaving children who’ve received cash gifts or mow lawns for pocket money unable to make purchases of any kind.
- Customers with Privacy Concerns. Many Americans use cash for small purchases and/or sensitive transactions. It is unsettling for some to think every purchase is being tracked and monitored. In addition, Americans have suffered through several security breaches at large corporations leaving consumers understandably hesitant to share their digital information
Every U.S. bank note is printed with the words: “This note is legal tender for all debts, public and private.” In a society that limits the use of cash, this would make those words meaningless… and would lock out a number of consumers from making purchases.
Giver your Customers the Freedom of Payment Choice and Easy Cash Access!
Contact BFC Enterprises today to get an ATM for your business. You may qualify for a free, turn-key ATM!
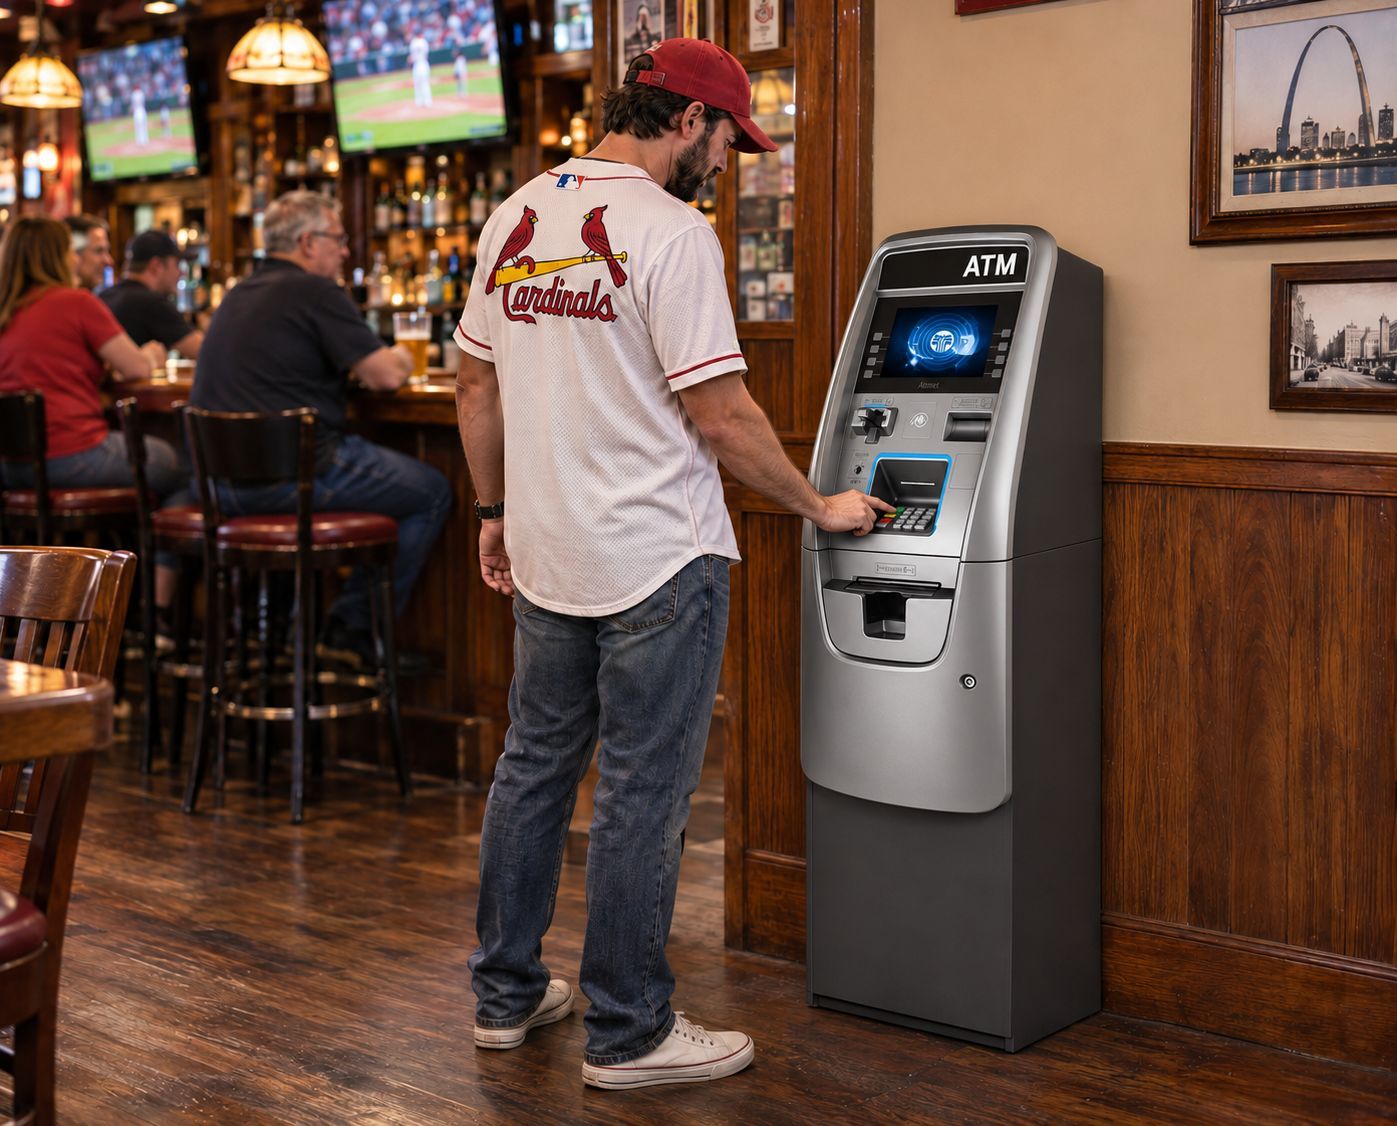
By Todd Farber, CEO, BFC Enterprises A few years ago, I got a call from a bar owner near Busch Stadium on a Friday afternoon. Cardinals fans were in town for a playoff weekend, and a customer had just told him his ATM wasn’t working. He was concerned. He expected fans coming and going before and after the games, with others settling in to watch on the bar’s TVs. He counted on the extra income the ATM brought in too, and we had just put a new sign in the window advertising it. I told him, “Let me see what we can do.” I pulled up our monitoring program, identified the issue and checked where our technicians were working. Within 10–15 minutes, I called him back. One of our technicians was servicing another machine nearby and had the part his ATM might need in the truck. Our tech arrived a little before 5 p.m. and got the ATM back in service. You can imagine the owner’s relief. He had a working ATM for the busy weekend ahead, and I had another reason to be proud of our team. They understood what was at stake for his business and pulled together to take care of him. To me, that’s just one example of the difference a local ATM provider can make. When you call, you aren’t just another open ticket, but instead you reach someone who knows your business and takes responsibility for helping you. We understand that an ATM outage can mean lost income and customers leaving to find cash. You’re counting on us, and we take that personally.

See how a Chesterfield, MO barber shop used a free ATM to cut credit card fees, offer cash discounts, increase cash tips and earn additional revenue.